FSL Blog · 23 Sept 2026
A $5M Seed now requires a $1B position
Seed math changed. If a fund needs its stake near $1B, your forecast has to support a multi-billion outcome and a clear path to roughly $1B ARR.
A $5M Seed now requires a $1B position
I keep seeing founders pitch a "normal" seed as if we still have the same metrics of 2012. But it's 2026.
A $5M Seed (fairly normal in quick scalers) allows to scale, hire talent, and execute over the SaaS/AI GTM playbook. Just after pre-seed, with PMF, and before the more institutionalized Series.
It also has to answer a harder question on the other side of the table: can this check become a ~$1B position for the fund? Meaning: will their 15% to 20% stake be worth around $1B?
If not (or even if they suspect not), they'll pass.
Why the new metrics?
Outcomes at the top of the market got...insane. What 10 years ago was considered a great outcome, like a unicorn (one billion in $USD in value) today the north star moved to the one trillion, which is just 1000x times that.
Companies like OpenAI, Anthropic, and SpaceX, while outliers, are or will be valued above the trillion at IPO (initial public offering). And this sets expectations for the rest of the startup ecosystem.
I used to see VCs look at TAM, see a few billion dollars of "market," and move on. Now they triple-check the $1B+ position. Does their ownership get there or not.
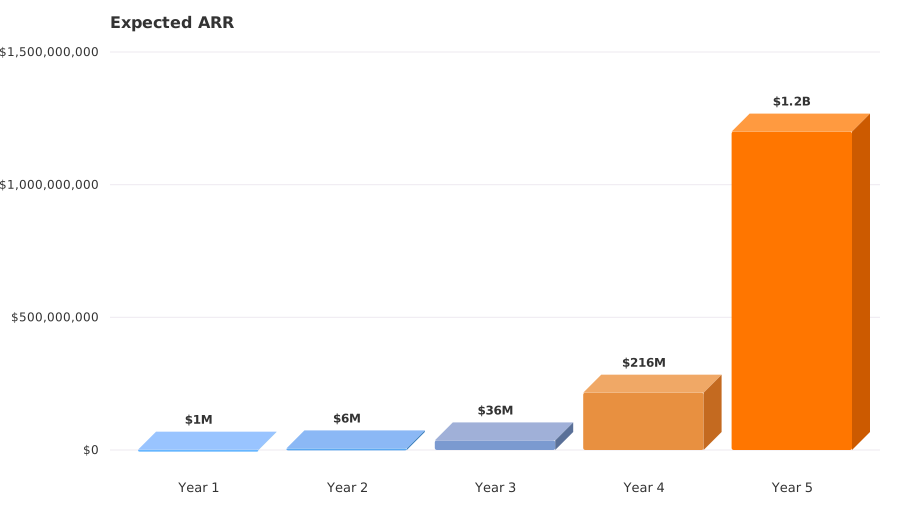
Do the ownership math with me. They enter at 15% to 20%. By the end you often model something closer to ~12% after dilution. A ~$1B stake at ~12% needs the company around an ~$8B outcome. So the deck needs a path to roughly $800M / $1.2B ARR. When I say the deck I don't mean the vibe of a spreadsheet, but the actual customer growth is telling that story.
The ARR path YoY
Since you need to get there by year 5...
- Year 1: $1M ARR
- Year 2: $6M ARR
- Year 3: $36M ARR
- Year 4: $216M ARR
- Year 5: $1.2B ARR
Roughly 6x a year. (Do you remember triple-triple-double-double? Well, Venture doesn't.)
You are competing against forecasts in the $1B to $1.5B ARR band inside 5 to 7 years.
If your stats don't support that, you won't qualify for VC-seed. Ofc you can still bootstrap. But if your plan considered raising VC to get that extra $1-2M to invest in marketing and ads, you have to change plans.
The only exceptions I can see
Two, maybe:
- Glorious past. Multiple exits. VP at big tech. The risk is mitigated, and they are okay in investing.
- Deeptech. Took years because of computation or hardware and you have patent or significant defensibility.
Everyone else will be measured against that YoY curve.
So put money into sales. When a seed partner talks ~$1B position, they are asking if your GTM can carry a billion ARR story.
How is your projection?
Not the hockey-stick slide with zero capacity plan.
The one you'd defend live: pipeline, conversion, hiring, year-by-year ARR. Does a 15% to 20% stake get near ~$1B or not.
If you want VC-seed, start there.