FSL Blog · 25 Sept 2026
Is VC mathing for you?
With $100 across 100 startups and a 2× fund target, you need to return ~17×. And this is only a simplification.
Is VC mathing for you?
A pattern you hear a lot in venture: ~75% of deals return nothing. ~7% of deals produce about 60% of the returns.
That is industry texture. Below is a simplified book so you can feel what those percentages do to a partner who has to return cash to LPs.
Sit in the partner seat
Imagine you are the partner.
You have $100 to invest across 100 startups.
Your goal is to 2× this. You need $200 back.
What the book looks like
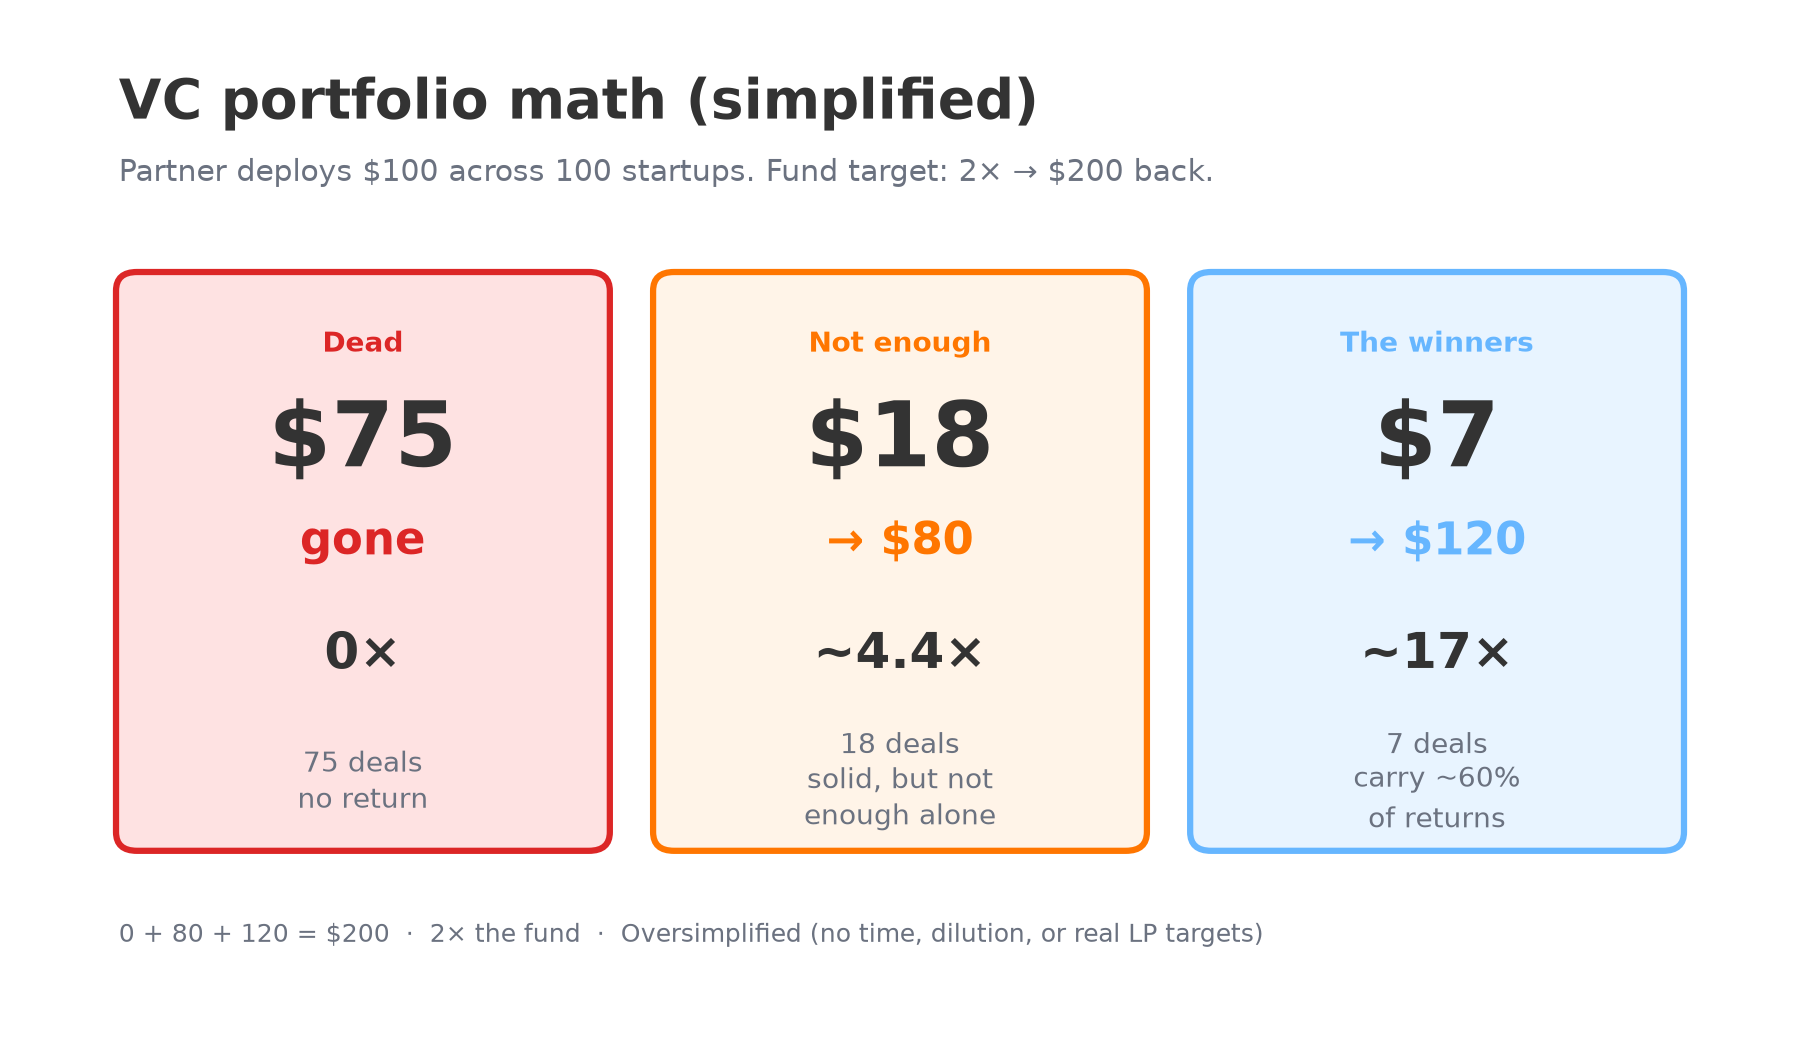
$75 are gone.
$7 will generate $120 (in our 2× example).
$18 will generate $80.
Check the fund math:
The “good” deals are not the winners
That $18 that on average generates ~4–5× ($80 / $18 ≈ 4.4×) which for a founder could be life-changing, is not considered a winner in this model.
That $7 that on average generates ~17–18× ($120 / $7 ≈ 17×), instead, is.
For numerical distribution, that $7 has seven different deals. Some will generate 6×, some 10× and maybe one 100×. This last one will be considered the actual winner.
And this is only a quick estimation, now add dilution, longer time horizons, extra capital injection and reinvestments... then it's not hard to grasp why a $5M Seed would need a $1B position (so 200×) to be considered a winner by venture capital.
So what does your plan have to look like?
Before you take a single dollar in venture, ask yourself: "Do I have a plan to get at least 17× back for each single dollar in?" And plan here means: customer growth, retention, LTV/CAC, YoY vs MoM conversion, pricing, etc.
This is an oversimplification. It does not take into account:
- time horizons
- dilutions
- actual fund targets (many funds aim higher than a clean 2×)
Still, the shape of the problem stays the same. A small number of outcomes have to do almost all of the work.
A $5M seed that needs to become a ~$1B position for the fund is asking for something like ~200× on the roadmap for that ownership story. Most companies will not get there. That is why the bar sounds insane from the founder side, and normal from the partner side.
I wrote more on the ownership and ARR path in A $5M Seed now requires a $1B position.
Is it mathing for you?
If your forecast cannot support a fund-making outcome, VC is the wrong machine for that plan. Bootstrap, stay lean, or raise on different terms.
If it can, stop optimizing for “solid” 4–5× language and start testing whether the GTM can carry the thin slice that actually returns the fund.
I heard a beautiful metaphor a few days ago on a VC podcast which resonated a lot: "Venture is like a train where the only thing that matters is the head of the train."